Reverse Mortgage in Huntington Beach: The Complete Guide to Private Jumbo & HECM Loans
- Jumbo Reverse Mortgage
- Huntington Beach
```
Private Jumbo & HECM Reverse Mortgages: A Huntington Beach Homeowner’s Equity Guide
How high-value Huntington Beach homeowners may be able to access home equity while continuing to live in the home they love.
Prepared by Frank Stiebel, Qualifying Mortgage Broker & Senior Equity Strategist
S.O.S. Loans, Inc.
```
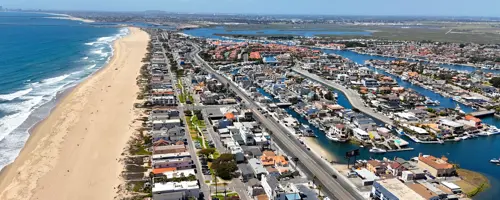
Reverse Mortgage Options for Huntington Beach Homeowners
```
Huntington Beach homeowners who have accumulated substantial equity may have financial options that are not available to the average homeowner. For seniors who own a valuable California residence, a reverse mortgage can potentially turn a portion of that equity into accessible funds without requiring the homeowner to sell the property.
The right strategy depends heavily on the home's value, the homeowner's age, existing mortgage balance, occupancy, financial circumstances and the type of reverse mortgage being considered.
Traditional HECM reverse mortgages may be appropriate for many homeowners. However, homeowners with higher-value properties may also want to investigate private Jumbo reverse mortgage programs designed for homes whose values exceed conventional HECM lending parameters.
For Huntington Beach homeowners with significant equity, the important question is not simply, "Can I get a reverse mortgage?" The better question is:
"Which equity strategy is most appropriate for my home, my financial goals and my estate plan?"
```
See How Much Home Equity You May Be Able to Access
```
Get a personalized discussion based on your property, mortgage balance and financial objectives. There is no obligation to apply.
One Important Feature: Non-Recourse Protection
```
Many reverse mortgage programs are structured as non-recourse loans. In general, this means the borrower or estate is not personally responsible for repaying more than the value of the home securing the loan, subject to the specific terms and requirements of the applicable program.
Because program rules differ, homeowners should review the specific loan terms and obligations with a qualified mortgage professional before making a decision.
```
HECM vs. Private Jumbo Reverse Mortgage
The biggest distinction for affluent Huntington Beach homeowners is often the value of the property. A HECM is insured by the Federal Housing Administration and follows federal program requirements. Private Jumbo reverse mortgages are proprietary programs offered by private lenders and may be designed for higher-value properties.
Feature | HECM Reverse Mortgage | Private Jumbo Reverse Mortgage |
|---|---|---|
Program Type | FHA-insured reverse mortgage program | Proprietary private reverse mortgage program |
Higher-Value Homes | Subject to the applicable HECM maximum claim amount | May accommodate substantially higher property values |
Borrower Requirements | Federal HECM eligibility requirements apply | Requirements vary by private lender and program |
Loan Proceeds | Available proceeds depend on age, home value, interest rate and other factors | May provide larger proceeds for qualifying high-value properties |
Best Fit | Homeowners seeking a federally insured reverse mortgage | Homeowners with substantial equity and higher-value residences |
```
Why Jumbo Reverse Mortgages Can Matter in Huntington Beach
Huntington Beach contains many properties whose market values can exceed the lending limits associated with traditional mortgage products. For homeowners with substantial equity, this can create an unusual situation: the homeowner may be asset-rich but still prefer not to sell investments or substantially reduce liquid assets.
A private Jumbo reverse mortgage may provide an alternative way to access a portion of that home equity. Depending on the program, proceeds may be available as a lump sum, line of credit or another permitted structure.
Available proceeds are not determined by property value alone. Age, occupancy, existing liens, property type, financial circumstances, lender requirements and current program terms can all affect eligibility and proceeds.
The Second-Position Reverse Mortgage Strategy
```
One of the more specialized strategies available to certain homeowners involves a reverse mortgage placed behind an existing first mortgage.
This can be particularly interesting when the homeowner has a favorable first-mortgage interest rate that they do not want to refinance or replace.
Instead of automatically paying off the existing first mortgage, a qualifying second-position structure may potentially allow the homeowner to preserve the existing financing while accessing additional equity.
Important: Second-position reverse mortgage availability is highly program-specific and subject to lender underwriting, lien requirements and sufficient remaining equity.
```
Your home's value may be only the beginning of the conversation.
``` EXPLORE MY REVERSE MORTGAGE OPTIONS ```
A Different Approach for High-Value California Homes
High-value reverse mortgage transactions can require a different level of analysis than a conventional homeowner equity loan. Property value, existing liens, trust ownership, estate objectives and the desired amount of liquidity can all influence which programs deserve consideration.
Frank Stiebel works with California homeowners who want to explore HECM and proprietary reverse mortgage alternatives, including strategies designed for higher-value properties.
The goal is not simply to determine whether a homeowner qualifies. The goal is to identify the structure that best fits the homeowner's objectives while clearly explaining the costs, obligations, risks and potential benefits.
How Huntington Beach Homeowners May Use Reverse Mortgage Proceeds
1. Retirement Liquidity
Accessing home equity may provide an additional source of liquidity during retirement, potentially reducing the need to sell other assets at an unfavorable time.
2. Investment Portfolio Management
Some homeowners may use home equity strategically to manage withdrawals from investment accounts. This should be evaluated with consideration for investment risk and tax consequences.
3. Home Improvements
Proceeds may potentially be used for remodeling, accessibility improvements, repairs or other major projects, subject to program rules.
4. Paying Off Existing Debt
Depending on the structure, reverse mortgage proceeds may be used to satisfy an existing mortgage or other eligible obligations.
5. Estate & Financial Planning
For homeowners with significant real estate holdings, home equity may be one component of a broader retirement, estate or liquidity strategy. Consult your financial, legal and tax professionals regarding your individual circumstances.
```
The Reverse Mortgage Process
Step 1 — Review Your Property
Begin with the home's estimated value, property type, occupancy and location.
Step 2 — Review Existing Financing
Existing mortgages, HELOCs and other liens can materially affect available proceeds and the structure of a potential transaction.
Step 3 — Compare Programs
Compare HECM and applicable private reverse mortgage programs based on the property and homeowner's objectives.
Step 4 — Review the Numbers
Review estimated proceeds, interest rates, fees, repayment requirements and other program terms before deciding whether to proceed.
```
Find Out What Your Huntington Beach Home Equity Could Do for You
A personalized equity review can help you understand whether a HECM, private Jumbo reverse mortgage or another equity strategy may fit your situation.
SEE MY POTENTIAL EQUITY OPTIONS
No obligation to apply.
```
Frequently Asked Questions
What is a reverse mortgage?
A reverse mortgage allows an eligible homeowner to borrow against a portion of the equity in a qualifying residence. Unlike a traditional mortgage, repayment is generally deferred until a specified triggering event occurs, subject to the terms of the loan.
What is a Jumbo reverse mortgage?
A Jumbo reverse mortgage is generally a proprietary reverse mortgage designed for higher-value properties. Availability, maximum loan amounts and eligibility requirements vary by lender and program.
Can I get a reverse mortgage if I already have a mortgage?
Potentially. Existing mortgage debt generally must be addressed as part of the transaction. Depending on the program, a reverse mortgage may pay off the existing loan, while certain proprietary programs may offer alternative structures subject to qualification.
Are reverse mortgage proceeds taxable?
Loan proceeds are generally not treated as ordinary taxable income because they are borrowed funds. However, reverse mortgage proceeds can interact with taxes, benefits and financial planning in different ways. Consult your tax or financial advisor about your individual circumstances.
Do I still own my home with a reverse mortgage?
In a typical reverse mortgage transaction, the homeowner retains ownership of the property, while the lender has a mortgage lien. The homeowner must continue meeting the obligations of the loan, which can include property taxes, insurance, maintenance and occupancy requirements.
How much can I borrow?
There is no single answer. Available proceeds can depend on age, property value, interest rates, existing liens, property type, program rules and lender underwriting. A personalized review is the best way to estimate potential proceeds.
```

Meet Frank Stiebel
Top Reverse Mortgage Broker in Orange County for Private Jumbo Structures
Frank Stiebel is a California Qualifying Mortgage Broker and senior equity strategist with S.O.S. Loans, Inc. He specializes in helping homeowners evaluate reverse mortgage and high-value equity strategies for California properties.
His work includes helping homeowners evaluate Private Jumbo Reverse Mortgages, second-position reverse mortgage structures, high-value home equity strategies and complex California properties.
For homeowners in Huntington Beach, Orange County and throughout California, Frank provides a direct point of contact for understanding available programs, comparing structures and determining whether a reverse mortgage strategy makes sense for their circumstances.
Frank's Areas of Specialization:
✓ Private Jumbo Reverse Mortgages
✓ Second-Position Reverse Mortgage Structures
✓ High-Value Home Equity Strategies
✓ Complex California Properties & Trusts
Speak Directly With Frank Stiebel
```
Your Home May Be One of Your Largest Financial Assets
Before selling investments, downsizing or refinancing a favorable existing mortgage, it may be worth understanding how much equity you could potentially access through a reverse mortgage strategy.
GET MY PERSONALIZED EQUITY REVIEW ```
Important Information: This article is provided for general educational and informational purposes only and does not constitute a commitment to lend, an offer of credit, financial advice, legal advice or tax advice. Reverse mortgage programs are subject to eligibility requirements, property requirements, lender approval, program availability, interest rates, fees and other terms and conditions.
Reverse mortgage borrowers remain responsible for complying with applicable loan obligations, which may include paying property taxes and homeowners insurance, maintaining the property, and satisfying occupancy requirements. Failure to meet applicable obligations may result in the loan becoming due and payable.
Private Jumbo reverse mortgage programs are proprietary products and are not FHA-insured. Program features, loan amounts, eligibility requirements and availability vary by lender and may change without notice.
Homeowners should consult their own financial, tax and legal professionals before making decisions involving retirement assets, real estate, trusts or estate planning.
S.O.S. Loans, Inc. — California lending and mortgage services. NMLS #2222125.
```